Survivorship Bias Is Distorting Every Best Practice You Copy
Survivorship bias overstates the typical U.S. stock fund's reported returns by roughly 1.6 percentage points a year, per CRSP: surviving U.S. stock funds averaged 8.8% over the decade ending 2003, and 7.2% once dead funds were counted. Every best practice you copy carries the same tilt.
Survivorship bias overstates the typical U.S. stock fund's reported returns by roughly 1.6 percentage points a year, according to the University of Chicago's Center for Research in Security Prices: surviving U.S. stock funds averaged 8.8 percent over the decade ending 2003, while counting the funds that quietly died dropped that to 7.2 percent (Wall Street Journal via NYU Stern). The same distortion sits underneath almost every best practice you copy. You study the winners because the winners are the only ones still around to study.
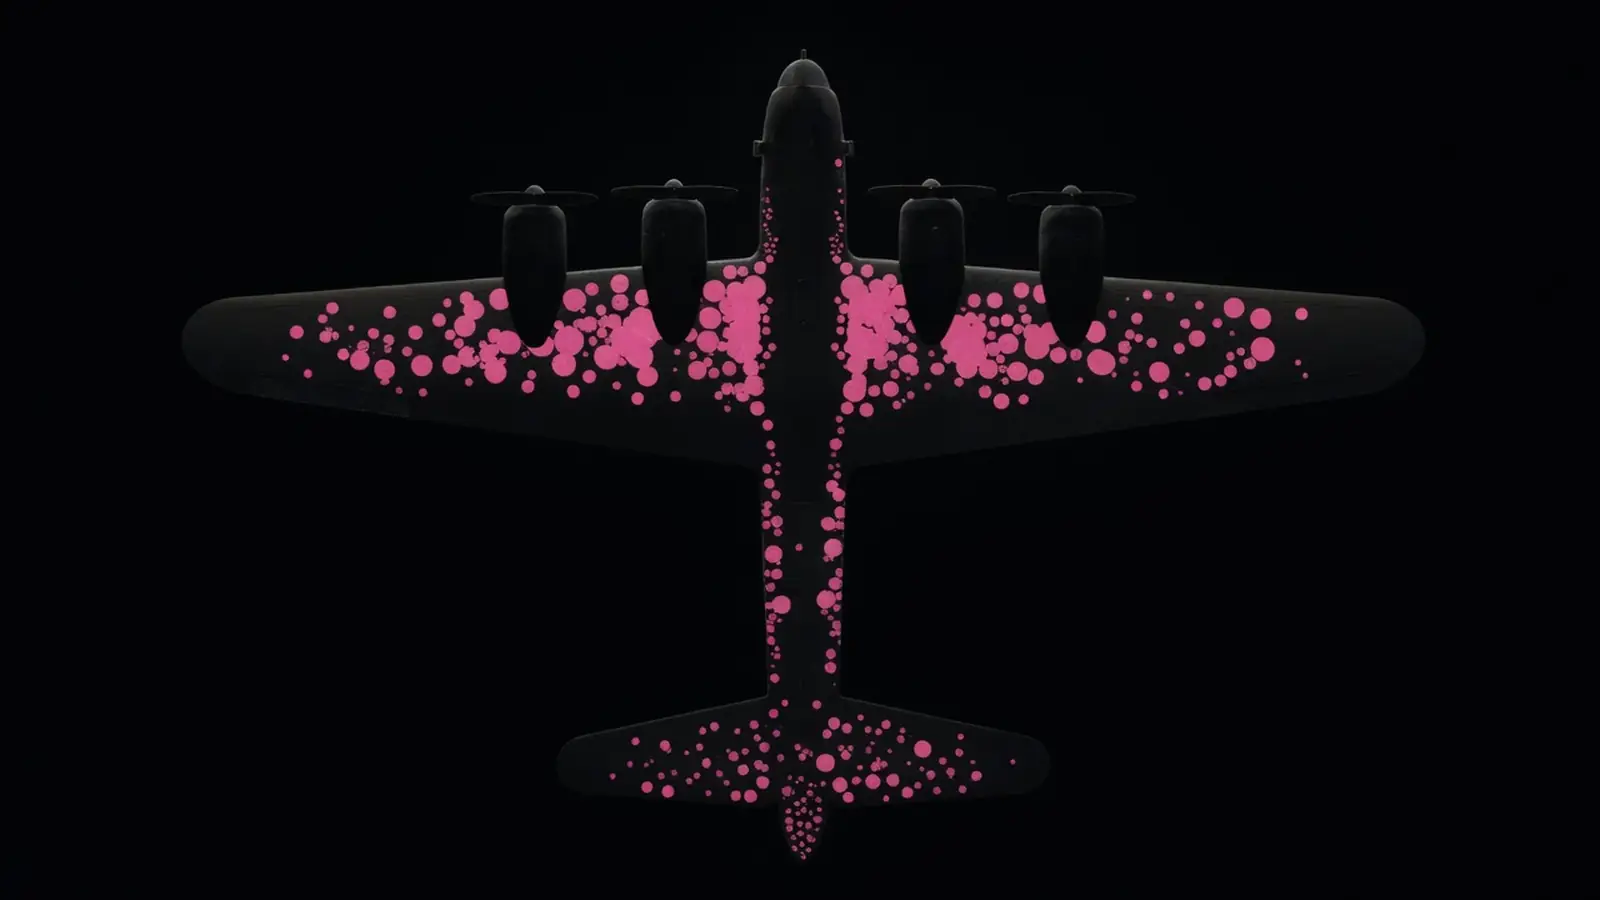
The returning bombers showed damage everywhere except the engines, which is precisely where the armor needed to go.
I study behavioral psychology because these errors are so quiet. Survivorship bias does not feel like a mistake. It feels like doing your homework. You read the case studies, you note what the successful companies had in common, you adopt it. The flaw is invisible because the counterexamples were removed from the data before you ever saw it.
The short version: survivorship bias is what happens when you learn only from the cases that lasted. Funds, companies, stocks, traders and tools that failed drop out of the record, so whatever is left looks better than the real odds. Before you copy a best practice, run these checks:
Ask who tried the same thing and failed, and go find them.
Check whether the dataset still includes the closed, delisted, churned or departed cases.
Discard any trait the losers shared with the winners.
Discount long, dramatic success stories the most, because they outlasted the most competitors.
Prefer one boring base rate over ten vivid anecdotes.
The bombers that came back were the wrong data
The cleanest illustration comes from World War II. The U.S. military wanted to armor its bombers against enemy fire, but armor is heavy, so it could only go in a few places. Officers examined planes returning from missions, mapped where the bullet holes clustered, and proposed reinforcing those spots.
Abraham Wald, a statistician with the Statistical Research Group at Columbia University, saw the error. The damage on returning planes marked the hits an aircraft could absorb and still fly home. The engines, which came back relatively clean, were not safe. Planes hit there simply never returned to be counted (Wikipedia: Abraham Wald).
Wald's insight was to reconstruct the damage distribution for all aircraft that flew from data on only the aircraft that returned, and his work is now considered seminal in the young field of operational research (Wikipedia: Survivorship bias). The armor went where the bullet holes were not. That single reframe is the whole discipline: the sample you can see is filtered, and the filter is exactly the thing you are trying to understand.
What survivorship bias actually is
Survivorship bias is a statistical error that comes from concentrating on the entities that passed a selection process while overlooking the ones that did not (Wikipedia: Survivorship bias). The selection process is usually invisible. Failed companies stop publishing. Dead funds get scrubbed from the databases. Founders who followed the same playbook and went under do not write memoirs.
The mechanism matters because it explains why the bias is so durable. It is not that people ignore failures out of laziness. The failures are structurally absent. You cannot interview a company that no longer exists, so the interview list is pre-filtered toward success before anyone asks a single question. I wrote more about how invisible filters like this steer decisions in the bias you don't see is the one making your technology decisions.
Psychology adds a second layer. In my work, the surviving case also gets the most airtime, because a story with a clear winner is easier to retell than a spread of mixed outcomes. The data filter removes the failures, and then the way we share stories amplifies the survivors that are left. Survivorship bias in psychology terms is a selection problem first and a memory problem second, and both push in the same flattering direction.
Why "best practices" are a survivor's story
A best practice is a pattern observed among the people who succeeded. That sounds authoritative until you ask the second question: how many companies did the exact same thing and failed? If you never checked, the pattern explains nothing. A trait shared by winners and losers alike is not a cause of winning.
The most-sold business books have this problem baked in. In Search of Excellence studied 43 companies that were already known to be excellent and then extracted eight shared attributes. Good to Great selected 11 companies after seeing four decades of stock performance, then reverse-engineered the traits. The Pomona College economist Gary Smith points out that this is history dressed as prediction, because the companies were chosen precisely because they had already won (Scientific American).
The follow-up is more damning than the setup. Of the 35 publicly traded companies in In Search of Excellence, 20 later underperformed the market (Scientific American). The traits did not travel. They were coincidences that happened to co-occur with success in one window of time, and copying them offered no protection at all. When a competitor's playbook looks obviously correct, that is often the sign to slow down, which is the case I make in watch competitors, don't build their roadmap.
The same article reports that six of the 11 Good to Great companies went on to underperform the overall market from 2001 through 2012, as Smith tallied it (Scientific American, 2014). Smith's fix is simple to state: pick the companies at the start of the test period, using rules you set before you look at how they did, and then watch what happens.
The number that shows how large the gap is
Finance quantifies survivorship bias better than almost any other field, because funds are counted precisely and then deleted precisely. When a fund performs badly it gets liquidated or merged away, and its record disappears from the databases advisers use to research live funds. What remains is a lineup of survivors, which looks stronger than the real population ever was.
The academic estimates are consistent. Carhart, Carpenter, Lynch and Musto, working from all known diversified U.S. equity mutual funds from 1962 to 1995, found the annual bias rises with the length of the sample, from 0.07% for one-year samples to about 1% a year for samples longer than 15 years (Review of Financial Studies, 2002). A more recent analysis by Dimensional found that for U.S. equity funds from 1991 to 2020, survivorship bias overstated the median fund's annual alpha by about 0.60 percentage points: the median fund's alpha went from -1.44% a year to -0.84% a year when only survivors were counted (Dimensional, "Why Worry About Survivorship Bias?", December 31, 2020).
The same Dimensional study shows how often funds vanish. About 100 U.S. equity funds were liquidated or merged each year, roughly 5% of the funds alive at the start of any year, and 275 disappeared in 2009 alone. Counting only survivors, 4.5% of funds earned a reliably positive alpha. Counting every fund, that share fell to 2.4%, which is below the 3.2% you would expect from luck alone in a sample that size (Dimensional, "Why Worry About Survivorship Bias?", December 31, 2020). Survivorship bias in finance roughly doubles the apparent number of skilled managers.
The lesson reaches well beyond funds: the difference between the survivors and the full population is measurable, large, and always in the flattering direction. Any dataset built only from things that lasted carries the same upward tilt, whether it is funds, startups, or the tools your peers say they love.
Survivorship bias in trading and backtesting
Survivorship bias in trading usually enters through the data you test on. A backtest that starts from today's list of stocks has quietly removed every company that went bankrupt, was delisted or was bought out along the way. Wikipedia's entry gives the standard example: a backtest of S&P 500 dividend payers back to 1990 that uses only the current index members carries survivorship bias, because the members that fell out of the index are missing (Wikipedia: Survivorship bias).
Even good databases can carry a version of survivorship bias. Tyler Shumway showed in the Journal of Finance that stocks delisted for bankruptcy and other negative reasons were generally surprises, and that correct delisting returns were missing for most of them in the CRSP database since 1962. Using over-the-counter prices, he found the omitted returns were large (Shumway, 1997). A strategy that never has to absorb the last, worst month of a dying stock will look better on paper than it can trade.
If you build or buy a trading strategy, a few habits correct most survivorship bias:
Test on a point-in-time universe: the stocks that were actually tradable on each date, including those that later died.
Make sure delisting returns are included, or apply a documented correction when they are missing.
Ask a vendor whether its track record includes the strategies it retired. A shop that launches ten models and markets the three that worked is showing you survivors.
Judge a manager on every fund they ran, which is exactly what Dimensional recommends: evaluate a manager on the full set of funds, including those no longer available.
Survivorship bias in hedge funds, and its cousin backfill bias
Hedge funds report to commercial databases voluntarily, which makes survivorship bias stronger there. William Fung and David Hsieh analyzed the TASS hedge fund database as of September 1999, which held 1,120 surviving and 602 defunct funds. From 1994 to 1998 the surviving portfolio returned 13.2% a year against 10.2% for all funds observed, so they put survivorship bias in hedge funds at 3.0% a year (Fung and Hsieh, working paper published in the Journal of Financial and Quantitative Analysis, 2000). Of the defunct funds, 60% were liquidated, 4% merged, and 28% were removed because the manager simply stopped reporting.
The same paper measured a second distortion. Funds usually trade for a while on their own money before they join a database, and when they join, the vendor can backfill that history. Managers with a bad start rarely bother to list. Fung and Hsieh dropped each hedge fund's first 12 monthly returns and found this "instant history" bias, now usually called backfill bias, added about 1.4% a year to reported returns. Stack the two together and the industry averages you see in marketing can sit several points above what a typical investor experienced.
There is also a reverse version. Juhani Linnainmaa of the University of Chicago showed that because funds tend to close after a run of bad luck, a fund-by-fund estimate of a manager's skill from even a survivorship-free dataset ends up biased low, by roughly 1 percent a year in the mean (Linnainmaa, "Reverse Survivorship Bias," 2010 working paper). Reverse survivorship bias sits alongside the ordinary kind, and together they show that the cutoff rule itself shapes the numbers in both directions, so you have to know how a dataset decided who stays in.
What should you know about survivorship bias in politician trade tracking data?
Congressional stock trade trackers are popular, and they inherit every problem above plus a few of their own. The raw data comes from the STOCK Act, which requires members, officers and certain employees of the House to disclose transactions over $1,000 in certain securities by the earlier of 30 days from learning of the trade or 45 days from the trade date (House Committee on Ethics, 2026 instruction guide). Amounts are reported in value categories set by the Ethics in Government Act, starting at not more than $15,000 and running up to greater than $50,000,000, so no tracker knows the exact size of most trades.
Here is where survivorship bias in that data creeps in:
Leaderboards show the winners. A ranking of "best-performing" members is a survivor list by construction. With hundreds of filers, a handful will beat the market by chance in any given year, and those are the names that get shared.
People leave. Members retire, lose elections or resign. A tracker that shows only current members, or a backtest that uses today's roster, drops everyone who left, along with their trades.
The timing is late and fuzzy. A copy strategy can act only on the filing date, up to 45 days after the trade, while many published return charts quietly start from the trade date.
The amounts are ranges. Any dollar return built from category midpoints is an estimate, and small trades in the lowest category can carry the same weight as large ones.
The honest test is the same one Wald ran. Count every filer and every disclosed trade, use the date the public could actually see it, and compare against a plain index over the same window.
More examples of survivorship bias
Once you know the shape of survivorship bias, you see it everywhere. A 1987 study in the Journal of the American Veterinary Medical Association looked at 132 cats treated for falls from high-rise buildings over five months (Whitney and Mehlhaff, 1987). Surviving cats from shorter falls had worse injuries than those from taller falls, and one proposed explanation is survivorship bias: cats killed in a fall are far less likely to be brought to a veterinarian at all, so they never enter the data (Wikipedia: Survivorship bias).
Trading rules can carry survivorship bias too. William O'Neil built his CAN SLIM method by studying the biggest stock market winners, 1,000 top performers from 1880 through 2009 in the fourth edition of his book, and his best-known rule tells investors to sell if a stock drops 7% or 8% below the purchase price (AAII Journal, 2016). A loss limit is sensible risk control. The point is that a study of past winners tells you what winners looked like, and it cannot tell you how many stocks looked the same at the buy point and then failed.
The writer David McRaney summed up the business version: the advice business is a monopoly run by survivors (Wikipedia: Survivorship bias). Conference keynotes, podcast guests and case-study pages are drawn almost entirely from people and companies that made it, which is why a room full of confident advice can still be a poor guide to your odds.
Survivorship bias works like an archive where only the success files are ever pulled; the closed drawers hold the failures that would change the answer.
Where it hides in a small business
The trap shows up the moment you make a decision by looking at who succeeded. You ask which CRM the fast-growing companies use, which tech stack the unicorns chose, which automation the efficient teams adopted. Every one of those questions samples only survivors, and every answer is tilted.
Consider the founder-drops-out-of-college story. It survives because the handful who dropped out and won are visible and celebrated, while the far larger group who dropped out and failed left no trace. The advice "drop out and build" is a survivorship artifact. The same shape appears when someone insists a risky architecture is fine because a famous company runs it at scale. The companies that tried it and collapsed are not on the panel.
Hiring copies the same shape. A job posting that lists the traits of your best current employees is a survivor sample, because it never captures the people who had those exact traits and still did not work out. So is a marketing channel decision made by asking which channel your successful peers swear by, when the peers who tried the same channel and got nothing are not in the room to warn you.
It compounds with the biases I have written about elsewhere. You keep a failing homegrown system because you built it, which is the endowment effect, and you keep pouring money into it because you already have, which is the sunk cost fallacy. Survivorship bias supplies the justification: you point to the one company where that same stubborn bet paid off and quietly ignore the graveyard of companies where it did not.
Your own records can carry survivorship bias too. Some CRMs and billing tools archive or delete customers who cancelled, so a report on "average customer lifetime value" drawn from active accounts describes only the customers who stayed. The same goes for a survey sent to current clients, or a dashboard of the campaigns that are still running. Keeping closed accounts and stopped projects in the data, with a clear status, is a basic design choice in how a business's data pipelines are built, and it is the only way the numbers can show you what churn and failure actually look like. I go deeper on tracing a number back to its source in data lineage: where your numbers come from.
Survivorship bias in AI and the evidence you keep
AI tools invite survivorship bias at a faster pace. The demo shows the answers that worked, the case study shows the team that saved hours, and the screenshot that goes viral is the one good output out of many tries. If you judge a tool from those, you are judging survivors.
The correction is to keep and test the failures on purpose. When you build a test set to check an AI system, include the edge cases, past failures and inputs it should refuse, which is how a well-built golden dataset is defined. When an AI agent acts in your systems, its log should record whether each action finished, failed or was refused, so the misses are on the record next to the wins; that is the standard for an AI agent audit trail. And when someone claims a tool saves time, ask whether the figure is averaged across everyone, users and non-users alike, or drawn from the people who loved it. Brian Gagne walks through that exact distinction in does AI actually save time at work. I cover the practical side of checking outputs in how to audit what AI is actually doing.
Correcting survivorship bias in AI testing means keeping the failed runs in the rack, not only the ones that glowed.
How to correct for the missing data
Wald's method was to model the planes that never came back. You can do a plain-language version of the same thing. Before you copy a practice, ask who tried it and failed, and go looking for them on purpose. If you cannot find any failures, that is not proof the practice works. It usually means the failures were filtered out before they reached you.
The finance data gives you a rule of thumb for how much to discount. If survivorship inflates fund returns by around 1 to 1.6 percentage points a year, and the effect grows with the length of the sample (Carhart and colleagues), then a success story spanning many years in a turbulent market deserves the heaviest discount of all. The longer and more dramatic the survival, the more competitors it quietly outlasted, and the fewer of them you will ever hear about.
Invert the question. Instead of "what did the winners do," ask "what did the losers also do." If a trait shows up in both groups, discard it. This is close to running a premortem on borrowed advice: assume the best practice will fail for you and reason about why, which surfaces the conditions the success stories never mention. It pairs well with resisting the pull toward more, which I unpack in default bias and in choosing the tasks you should never automate.
Weight base rates over anecdotes. One vivid success story is a sample size of one, drawn from a pool you cannot see. A boring statistic that counts the failures too, like the fund numbers above, is worth more than any founder's origin story. Studying real behavior at population scale, not the highlight reel, is exactly why I study consumer behavior. And when a vendor's pitch leans entirely on customer success stories, remember that a testimonial page is a survivorship machine by design, a point that connects to why platform comparisons don't count as guidance. We write more about building on evidence rather than folklore across the Kief Studio blog.
A worked example: copying a peer's software choice
Illustrative example: say five owners in your local business group all run the same project management tool and love it. That sounds like strong evidence, and it is a textbook setup for survivorship bias. Now ask the survivor question. How many businesses in the group tried that tool and dropped it? Owners who switched away rarely bring it up, and owners whose businesses closed are no longer in the group at all.
Suppose you ask around and learn that eight businesses tried it, five kept it and three left within a year, two of them because it could not handle their invoicing. Your sample just changed from five out of five to five out of eight, and you now know the specific condition that sank the others. If invoicing matters to you, that is the most useful fact in the whole conversation, and the survivors would never have told you. The same three questions work for any copied choice: who else tried it, what happened to them, and what did they have in common.
Frequently asked questions about survivorship bias
What is survivorship bias in simple terms?
Survivorship bias is the error of drawing conclusions only from the things that made it through a selection process, while ignoring the things that did not. Because failures tend to disappear from the record, the survivors you can study look more impressive, and more representative, than the full population ever was.
What is the airplane example of survivorship bias?
During World War II, statistician Abraham Wald analyzed damage on returning bombers. Officers wanted to armor the areas with the most bullet holes, but Wald realized those were the survivable hits. The armor belonged where the returning planes showed no damage, because planes hit there had been shot down and never came back to be measured.
How does survivorship bias affect best practices?
A best practice is a pattern spotted among companies that succeeded, but it rarely checks whether failed companies did the same thing. If winners and losers share a trait, that trait does not explain success. Popular studies like In Search of Excellence and Good to Great selected companies after they had already won, and many of those companies later underperformed the market.
How do you avoid survivorship bias in decisions?
Go looking for the failures on purpose before copying anyone. Ask what the companies that also tried this and lost had in common, weight base rates over vivid anecdotes, and treat any dataset that excludes closures or dropouts as tilted upward. Modeling the missing cases, the way Wald did, is the core correction.
Why is survivorship bias hard to notice?
The bias is structural, not lazy. The counterexamples are physically absent from the data: dead funds are deleted, closed businesses stop reporting, and failed founders write no books. Because the sample arrives pre-filtered toward success, doing thorough research on it can still leave you with a distorted conclusion.
What are examples of survivorship bias?
The classic ones are Wald's returning bombers, mutual fund databases that drop dead funds, business books built on companies that had already won, and college-dropout founder stories. Others include backtests that use only today's index members, hedge fund averages that omit funds that stopped reporting, and a 1987 veterinary study of cats in high-rise falls where the cats that died rarely reached a clinic.
What is the WWII plane fallacy?
It is another name for the bomber example. Officers proposed armoring the parts of returning planes that had the most bullet holes. Abraham Wald pointed out that the planes hit in other places, especially the engines, had not come back, so the armor belonged where the survivors showed the least damage.
How does survivorship bias affect trading and backtesting?
A backtest built on the stocks that exist today leaves out every company that was delisted, went bankrupt or was acquired, so the strategy never takes those losses. Use a point-in-time universe that includes the dead stocks, include delisting returns, and judge any track record on every strategy the manager ran, including the retired ones.
What is the 7% rule in trading?
It usually refers to William O'Neil's rule to sell a stock if it falls 7% or 8% below the price you paid, as described in his CAN SLIM method (AAII Journal, 2016). It is a loss limit. O'Neil derived his method from studies of past big winners, so it is worth testing on a full universe of stocks, losers included, before trusting any claimed results.
What is bias trading?
The phrase usually describes trading decisions skewed by a cognitive or data bias rather than by evidence. Survivorship bias is one of the most common, because traders study the strategies and traders still standing. Confirmation bias, overconfidence and loss aversion are others that show up in the same decisions.
How big is survivorship bias in hedge funds?
Fung and Hsieh estimated survivorship bias in hedge funds at about 3.0% a year for 1994 to 1998, using the TASS database, with a further 1.4% a year from backfill (instant history) bias. Both inflate the averages, because funds that fail or start badly tend to stop reporting or never list.
What is backfill bias?
Backfill bias is a close cousin of survivorship bias. It happens when a fund joins a database and its earlier track record is added after the fact. Funds that start badly seldom join, so the backfilled histories are mostly good ones. Fung and Hsieh measured it at about 1.4% a year in hedge fund returns by dropping each fund's first 12 months.
What is reverse survivorship bias?
Reverse survivorship bias is the opposite tilt. Because funds tend to close after bad luck, measuring each manager's skill from their full record can understate it. Juhani Linnainmaa estimated the effect at roughly 1 percent a year in the mean. It sits alongside ordinary survivorship bias, and both show that the rule for who drops out shapes the numbers.
Is survivorship bias a problem in AI tools?
Yes. Demos, case studies and viral screenshots show the outputs that worked. Test an AI tool on a set that includes edge cases and past failures, keep a log of actions that failed or were refused, and ask whether time-savings figures average across all users or only the enthusiastic ones.
In a famous experiment, owners demanded twice what buyers would pay for the same mug. That's the endowment effect, and it quietly distorts the cloud versus self-hosting decision in both directions. The fix is to decide as if you owned neither option.
In a set of experiments published in 2011, people who assembled a plain IKEA storage box valued it 63 percent higher than an identical prebuilt one. The IKEA effect, named by the researchers who ran that study, is the bias that makes you overvalue what you built yourself. It quietly...
A premortem assumes a project has already failed, then asks why. Imagining the failure as settled raises a team's ability to correctly identify reasons for a future outcome by about 30 percent (Mitchell, Russo, and Pennington, Journal of Behavioral Decision Making).